This guide explains accounts receivable and how to manage it using practical, objective methods aligned with industry standards. It defines key terms commonly searched alongside “Receivables Investopedia,” explores why receivables matter for cash flow, and clarifies how buyers evaluate credit and collections risk. Readers also get a structured comparison, requirements, and FAQs.
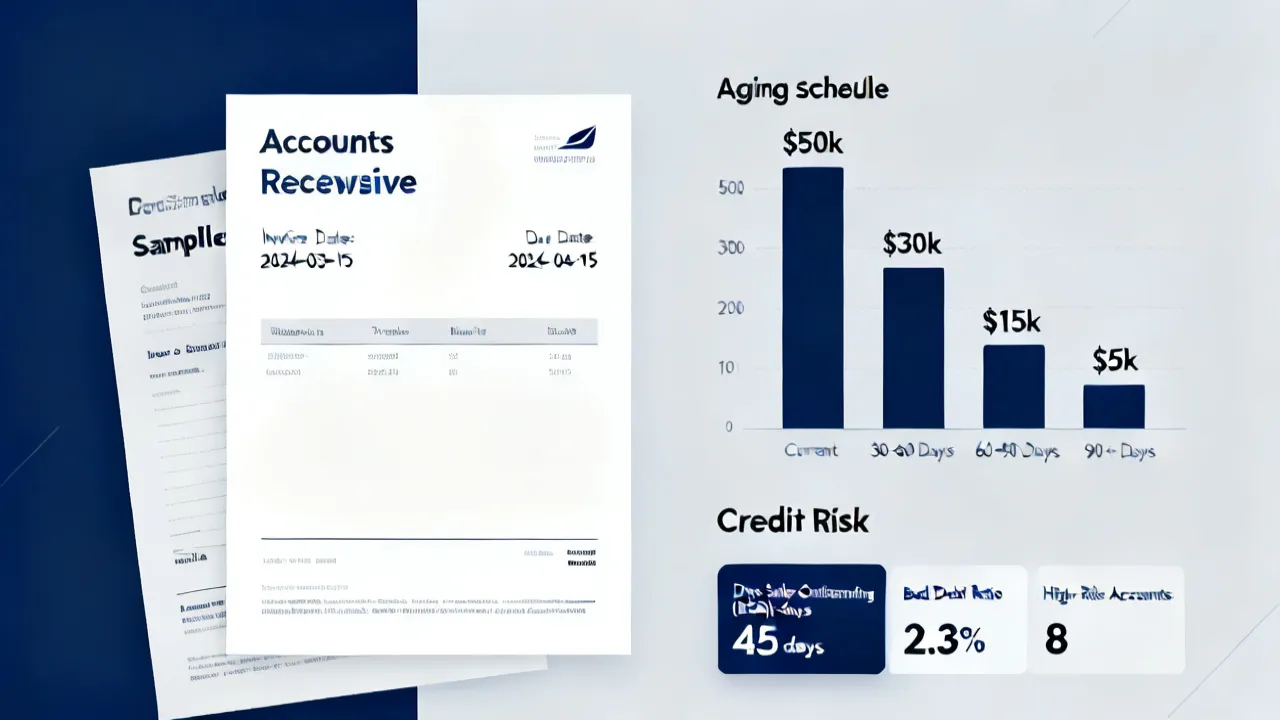
Accounts receivable is the category of Receivables Investopedia-type readers often start with when they learn how revenue turns into usable cash. In practice, managing receivables means setting clear credit terms, tracking invoices through collection, assessing customer risk, and applying consistent follow-up. When done well, it stabilizes working capital and reduces the likelihood of write-offs; when done poorly, it can create “paper profitability” while cash remains tied up in unpaid invoices.
Even if your company sells on account—whether through B2B contracts, recurring subscriptions, or large one-off deliveries—the operating reality is the same: you must convert receivables into cash on a predictable timeline. This guide focuses on how that process works, what decision points matter very, and what conditions typically need to be met to execute a sound receivables program.
It’s worth emphasizing the cultural shift: receivables management is not merely an accounting period activity (“close the books and record the balance”), nor is it solely a collections function (“send reminders until they pay”). Instead, it is a whole operational system that starts at the moment you agree to sell on credit and continues through invoicing accuracy, dispute resolution, and cash application. Each step creates either friction or momentum toward payment.
Companies that treat receivables as a cash-flow discipline tend to notice a common pattern: the majority of collection problems are not random. They correlate strongly with preventable causes such as unclear contract terms, billing that doesn’t match purchase orders, delivery confirmations missing details, slow approvals, inconsistent dispute handling, or payment instructions that are hard to follow. When teams systematically reduce those friction points, the receivables balance becomes a byproduct of a well-run sales-to-cash process rather than a mystery the finance team has to “chase.”
In standard financial reporting, accounts receivable represents amounts owed by customers for goods or services already delivered, but not yet paid. It is typically classified as a current asset when expected to be collected within a year (or the normal operating cycle).
Conceptually, receivables connect three systems:
Readers searching “Receivables Investopedia” are often looking for a clear definition, but the more important question is usually operational: how do we prevent receivables from becoming an avoidable liquidity problem?
To answer that operational question, it helps to separate “what the balance says” from “what the balance is doing.” A receivables balance can look stable while cash conversion deteriorates; for example, if payments shift from 30 days to 75 days, the total balance might not change dramatically at first, but your working capital requirement will rise because more money is stuck in invoices longer. Conversely, a receivables balance can rise even when you’re doing well, if you grew aggressively or moved to longer payment terms—so you must interpret the balance in context.
Accounting definitions provide the language, but the linked systems provide the levers. Credit management controls who you let into the system and under what terms. Invoicing controls whether the system is able to start the payment clock cleanly. Collections controls whether the payment clock ends with cash or with disputes and delays. And behind those three levers sits a final, often underestimated mechanism: payment application. If your company cannot apply customer payments accurately to the correct invoice, it can create “false delinquency” even when cash is received.
In short, receivables management is an integrated loop:
When any part of that loop breaks, your receivables system starts producing predictable symptoms: higher DSO, aging creep, increased allowances, more write-offs, and more time spent by staff in manual work.
Receivables are not cash. They are a claim on cash—often with a time lag. If customers pay late, the company may still have payroll, inventory, rent, and tax obligations due now. This is where receivables management becomes central to liquidity planning.
Two risks frequently shape receivables outcomes:
To address these risks, organizations commonly use an aging analysis, credit limits, and allowance estimation approaches under applicable accounting frameworks. The exact mechanics depend on jurisdiction and reporting standards (e.g., IFRS vs. US GAAP), but the objective remains consistent: represent expected losses and maintain credible cash projections.
Liquidity is the bridge between accounting and operations. Imagine a simple scenario: you invoice $1,000,000 in March with net terms of 45 days. Under the best-case timeline, you collect in early May. Under a realistic but deteriorating scenario, collection shifts into late June or July. Even if your revenue is “earned,” your cash requirement might grow by 1–2 months of working capital, which can strain credit lines, delay payments to suppliers, and force costly borrowing. In that sense, receivables are a financing decision—even when the company never formally chooses to borrow.
Many teams underestimate how receivables convert into liquidity pressure through three specific channels:
Dispute risk is particularly important because disputes can turn a manageable delay into a structural issue. For example, if billing depends on correct delivery confirmation but your shipping system does not consistently attach proof-of-delivery documents, customers may believe they have received something they did not order or delivered later than the contract requires. Even when you ultimately correct the invoice, the delay may have already passed the customer’s internal payment cycle window, pushing payment into the next month or quarter. That creates a predictable “aging spike” that looks like collection failure but is often a billing-data failure.
Risk exposure doesn’t just show up in write-offs. It shows up in the speed and volatility of your cash conversion cycle. A mature receivables program treats that volatility as a metric, not as an unavoidable side effect.
From an industry perspective, the strongest receivables outcomes typically come from process discipline rather than heroics. Teams succeed when they treat collections as an operational workflow with measurable signals and clear ownership.
Key success factors include:
When these elements are missing, receivables tend to drift—aging increases, allowances grow, and cash planning becomes less reliable.
To expand on “success” vs. “failure,” consider what “heroic collections” looks like operationally. Heroics often includes late-night calls, repeated emails without clear resolution ownership, and ad hoc agreements to accept partial payments without consistent documentation. While these tactics might recover cash in the short term, they weaken the system long term because they don’t fix the root causes: invoice errors, credit policy gaps, slow internal response times, and unclear evidence packages. In mature organizations, you’ll see fewer “random acts of follow-up” and more “tickets that move through a workflow.”
Mature receivables programs also have a strong feedback loop from outcomes back into process design. If aging trends show that certain invoice types consistently become disputed, the team investigates upstream causes: wrong tax handling, missing contract clauses, inconsistent milestone acceptance criteria, or unclear service start dates. Then they adjust invoicing controls and customer-facing documentation. This reduces disputes, which reduces aging, which improves cash conversion, which improves liquidity. That’s the virtuous cycle.
Failure programs often have the opposite loop: the finance team records allowances and write-offs, but the company never changes the billing process or customer onboarding procedure. Over time, the company becomes accustomed to high DSO and treats it as “normal” for the industry. But DSO is not destiny. Even in industries with inherently slower payment behavior, there is usually meaningful room to improve through clarity, evidence, and workflow discipline.
Additionally, a mature program understands that customers are not always “refusing to pay”; they may be waiting on internal approvals. If you have correct invoices but poor integration with customer systems, or if payment instructions are inconsistent, the invoice can linger in “accounts payable review” for weeks. That’s why receivables excellence is often paired with operational excellence: better data, better controls, better communication. Credit risk is only one driver; operational friction is another major driver.
While the receivables balance is a snapshot, many organizations rely on operational metrics to anticipate trends. Common measures include:
For reliable context on working capital analytics, many practitioners also reference guidance from established accounting bodies and financial education sources. For example, Investopedia-style definitions are educational; however, companies should ground impairment and classification approaches in their applicable accounting standards.
To manage receivables like a cash-flow discipline, you usually track metrics in four categories: timeliness, quality, risk, and efficiency. Aging and DSO cover timeliness. Dispute rates and invoice correction cycle times cover quality. Allowances and charge-offs cover risk. Collections cost-to-collect and process throughput cover efficiency.
Below are additional metrics that advanced teams track to avoid being blindsided by “surprises”:
Another practical point: many organizations focus on DSO as a single number. But DSO is a composite that can hide different problems. A stable DSO could occur while the company has shifted from “few big invoices paid late” to “many small invoices paid late.” The second scenario may create more work, more disputes, and higher operational load even if the average DSO looks fine.
Therefore, advanced receivables reporting often uses both value-based and count-based lenses:
When you track only one of these, you risk solving the wrong problem. For example, a business with a small number of very large invoices may have low invoice counts but high value-at-risk. Another business might have high invoice counts but lower value-at-risk per invoice. The appropriate response differs.
A robust system usually requires more than a finance department’s effort. It depends on shared responsibilities across sales, billing, customer service, and credit/collections.
Below are typical conditions/requirements that organizations implement, with the goal of making collection outcomes predictable.
| Component | What “good” looks like | Operational requirement |
|---|---|---|
| Credit policy | Consistent credit approvals, clear terms, and documented limits | Customer onboarding checks and renewal reviews |
| Invoicing controls | Invoice accuracy tied to purchase orders and delivery proof | ERP workflow with validation steps and exception handling |
| Aging & forecasting | Regular aging reviews and cash forecasts linked to expected collections | Scheduled reporting cadence and reconciliations |
| Collections playbook | Defined cadence for reminders and escalation paths | Workflow rules by customer segment and invoice status |
| Dispute management | Fast resolution and clear documentation to avoid stalled payments | Shared ticketing and evidence retention procedures |
| Impairment/allowance approach | Transparent method consistent with accounting requirements | Loss estimation methodology and review controls |
To make these requirements concrete, it helps to understand why each one matters and what happens when it is missing.
Credit policy is the gate. Without it, sales teams might offer terms based on competitive pressure rather than risk assessment. The result can be a receivables portfolio that looks “healthy” at inception but deteriorates quickly when customers face cash constraints. A credit policy also prevents inconsistent treatment of customers—something that can become a customer relationship issue (“Why do they give you 60 days but not us?”).
Invoicing controls are the ignition. Even if credit terms are correct, a wrong invoice slows collection because customers’ AP departments cannot process payments against erroneous documentation. Invoicing controls also reduce the need for credit memos and re-invoicing, which can create additional administrative load and confuse customers.
Aging & forecasting is the steering wheel. If you only review aging after month-end close, you are reacting too late. Timely aging review enables earlier fixes—such as correcting an invoice before it becomes “disputed for reasons that grow in complexity.” Forecasting should not just rely on historical averages; it should be informed by current aging distribution and expected dispute resolution timelines.
Collections playbook turns intent into execution. Without consistent cadence and escalation triggers, collections becomes inconsistent and dependent on individual employees. That leads to uneven results, higher turnover risk, and reduced accountability.
Dispute management is the shock absorber. Many disputes are legitimate (e.g., quantity discrepancies). Others are caused by unclear contract interpretation or missing paperwork. Either way, disputes require a controlled workflow: you need documented evidence, agreed resolution criteria, and an internal escalation path so that disputes don’t bounce between teams endlessly.
Impairment/allowance approach is the risk lens. Financial statement credibility relies on impairment estimation methodologies that are consistent with applicable standards. When allowance methods are weak, the company may understate or overstate risk, leading to management misalignment and potential audit issues. But beyond compliance, a sound allowance approach improves decision-making: it makes risk visible and measurable rather than a vague sense that “customers are struggling.”
Below is a practical, step-by-step guide that many finance and operations teams adapt. The emphasis is on measurable controls and repeatable execution.
That list is a strong baseline, but “building a defensible workflow” is often where companies need deeper operational detail. Below, each step is expanded with practical examples, common pitfalls, and implementation tips.
1) Standardize credit terms and approval rules
Start by defining what “standard” means: net-15, net-30, net-45, net-60, and so on. But standards aren’t enough; you need “why” behind each term. A good credit policy ties terms to customer risk tier, which might be based on credit score, payment history, industry, financial stability indicators, and prior dispute behavior.
Implementation tips:
Common pitfall: granting extended terms because “the customer is important” without a structured exception policy. This often creates hidden risk and inconsistent customer expectations.
2) Align billing with contract and delivery evidence
Invoice accuracy is not just “no typos.” It’s about aligning invoice line items with what the customer ordered and what you actually delivered or performed. For services, it often requires linking to acceptance criteria, time period coverage, or milestone sign-offs. For goods, it requires delivery documentation, quantities, and shipping details.
Implementation tips:
Common pitfall: manual billing adjustments outside the system that are not captured consistently, creating confusion during customer AP reconciliation.
3) Launch invoices promptly and confirm delivery
In many businesses, there is an unintended delay between delivery/performance and invoicing. Sometimes it’s because internal teams wait for paperwork completion. Sometimes it’s because invoicing is treated as an administrative task rather than a trigger for payment. But payment cycles begin when the customer receives and recognizes the invoice as valid.
Implementation tips:
Common pitfall: invoicing late “to match revenue recognition” rather than aligning with contract entitlements. Revenue recognition timing and invoicing timing can differ; receivables management must understand those differences.
4) Run an initial aging review soon after invoicing
Early aging review is where you catch preventable problems. If an invoice is not “current” in practice—even within the expected payment window—something is wrong. It could be an invoice delivery issue (customer didn’t receive it), a system integration issue (customer’s AP can’t match it), or a documentation mismatch.
Implementation tips:
Common pitfall: waiting for 30 days past due to start troubleshooting, by which time disputes and internal routing delays have compounded.
5) Segment customers and assign ownership
Not all receivables should be managed the same way. Segment customers by credit risk, dispute propensity, size, and payment behavior. Assign ownership so that every invoice path is clear: who handles current follow-ups, who handles disputes, and who escalates if payment stalls.
Implementation tips:
Common pitfall: splitting ownership by function only (collections owns delinquent invoices, billing owns disputes) without a clear “case manager” who ensures resolution moves forward.
6) Use a structured collections cadence
A collections cadence is a schedule of actions based on how long an invoice has been outstanding. The goal is to prevent accidental neglect while also protecting customer relationships. Mature organizations often prefer “structured persistence” rather than “random reminders.”
Implementation tips:
Common pitfall: contacting customers too aggressively without investigating whether the invoice is disputed. This can increase distrust and delay resolution.
7) Resolve disputes with documented evidence
Disputes are inevitable. The difference between a workable receivables program and a failing one is how quickly disputes move toward resolution and whether evidence is organized and accessible.
Implementation tips:
Common pitfall: resolving disputes verbally without documented confirmation. This increases the chance the customer reopens the issue, causing a cycle of delays.
8) Review credit exposure regularly
Credit exposure includes not just current receivables, but also future exposure based on pipeline volume and contracted obligations. If a customer increases order volume while their payment behavior deteriorates, your risk can grow faster than your accounting visibility.
Implementation tips:
Common pitfall: relying on the receivables balance alone. A customer can be “within limit” on day 1 while their next batch of deliveries is likely to be invoiced at higher risk.
9) Reconcile and refine loss estimation methods
Allowances are not a static decision. They should be refined based on actual outcomes. As you improve invoicing and dispute handling, your historical loss behavior may change—so your allowance approach should reflect that change.
Implementation tips:
Common pitfall: using outdated assumptions and not updating models or methodologies when business conditions shift.
10) Report outcomes and improve continuously
Reporting should inform action. It should answer: what is improving, what is worsening, and why? When receivables teams report only “balance” and “DSO,” they miss the drivers—dispute rates, invoice rework, credit limit breaches, unapplied cash, and collection efficiency.
Implementation tips:
Readers often begin with high-level definitions similar to those associated with “Receivables Investopedia.” While such explanations help conceptually, organizations need an operational approach that translates definitions into workflow controls.
| Approach | Primary focus | Strength | Common gap |
|---|---|---|---|
| Definition-focused learning | What receivables are and how they are presented | Builds baseline understanding for stakeholders | May not address how to reduce days past due |
| Process-and-controls design | Credit, invoicing accuracy, collections workflow | Improves cash conversion and reduces disputes | Requires cross-functional implementation and training |
| Risk and impairment modeling | Expected credit losses / allowance estimation | Improves reporting credibility and transparency | Can become complex without clear data governance |
In practice, the best-performing organizations blend all three: they understand the accounting meaning, they build controls that reduce avoidable disputes, and they model impairment responsibly. But they prioritize based on what is hurting cash flow right now.
For example, if your receivables aging is rising mainly due to disputes, then modeling impairment alone won’t solve the operational root cause. You need invoice accuracy controls and dispute workflow SLAs. Conversely, if customers are paying late because they don’t have liquidity, your process may already be strong, but credit risk mitigation and structured term adjustments become more important.
Another distinction is “where the data lives.” Definition-focused education tends to assume clean data for aging and balances. Operational execution reveals data problems: invoice mismatches, inconsistent customer master data, unclear payment remittance information, missing contract references, and manual workarounds. Addressing those issues is often the fastest path to improving DSO because it reduces delays at the source.
As a practical rule: if DSO worsens but the receivables balance doesn’t shift dramatically, you may have an invoicing or cash application issue. If the receivables balance increases and aging increases at the same time, it could be both growth plus credit risk. If balance stays stable but disputes increase, you may have quality issues rather than credit issues.
For objective and widely used references that inform how receivables are treated and assessed, consider the following sources. They support the conceptual and compliance backdrop for receivables management:
Note: This article is educational and does not replace professional accounting advice. Your approach should align with your jurisdiction and reporting standards.
Because receivables management intersects both operations and reporting, it’s helpful to ensure that operational definitions match accounting definitions. For instance, operational teams might label an invoice as “disputed” while the accounting team may treat it differently based on evidence and whether a credit note has been issued. If these definitions diverge, you can end up with reconciliation gaps, audit questions, and inconsistent allowance treatment. Aligning terms across teams reduces friction and improves both cash and reporting quality.
Many companies also benefit from consulting internal auditors or external advisors when implementing impairment approaches or when updating processes that affect financial statement disclosures. The goal is not to slow down operations; it’s to ensure that operational controls have a defensible audit trail.
No. Revenue is recognized when performance obligations are satisfied under applicable accounting rules. Accounts receivable is the unpaid amount owed by customers for that revenue (after invoicing or when entitlement is established). A company can have revenue recognized without immediate receivables, depending on contract terms and revenue recognition timing.
To connect this to operations: your billing schedule may not exactly match revenue recognition. Some contracts allow billing upon milestone acceptance; others require billing after delivery; and for services, billing may follow time periods. Receivables management must therefore understand “when cash should be expected,” not merely “when revenue is booked.” If you treat those as the same thing, forecasts can be wrong and receivables targets can be misaligned.
AR balance alone does not show collectability or timing. Aging (days past due) reveals which invoices are current versus at higher risk of delay or non-payment. This supports faster resolution and more accurate cash forecasting.
Additionally, days past due helps identify process problems. If invoices that are normally paid quickly suddenly become 20–30 days past due, that pattern can indicate a workflow breakdown (e.g., invoicing delay, incorrect payment instructions, or a change in customer AP process). AR balance may remain stable because the company is still generating revenue, but aging will reflect a change in collection behavior earlier than a monthly cash statement will.
An allowance represents expected credit losses or impairment related to receivables, based on reasonable and supportable information. The goal is to reflect that not all billed amounts are expected to be collected in full. The method and terminology depend on your applicable accounting framework.
From a practical receivables-management standpoint, allowances can also be used as a risk signal for operational improvements. For example, if allowances increase disproportionately in certain aging buckets, you might investigate whether invoice disputes are causing delayed payments beyond what is typical. While allowances are accounting measurements, they can still guide operational prioritization—especially when combined with dispute rates and payment behavior.
Errors can cause disputes, require credit memos, or force re-invoicing. Disputed invoices often stall payment, which increases aging and may contribute to higher impairment if not resolved promptly.
Billing errors also tend to produce a “second-order effect.” Even after you correct an invoice, customers may treat the correction as a new item in their AP workflow, which resets internal approval queues. That means small errors can have outsized effects on DSO and collection volatility, especially for customers who batch payments weekly or monthly.
A defensible policy typically includes: clear credit terms, documented escalation triggers, consistent communication schedules, dispute resolution procedures, and ownership across finance and customer-facing teams. The policy should be applied consistently and supported by records.
Defensibility also means you can explain your actions logically. If a customer disputes an invoice, a defensible policy ensures you have evidence and you handle the dispute within a structured timeline. If you decide to offer a payment plan or accept partial payment, the policy should document the rationale and ensure agreements are recorded and updated in systems.
Yes. Industries with longer billing cycles, milestone-based contracts, regulated service periods, or complex delivery documentation often need tighter invoicing controls and dispute-handling workflows. Retail and straightforward invoice-to-payment cycles may emphasize automation and prompt billing.
Even within an industry, the sales model matters. A SaaS subscription with monthly billing behaves differently from a project-based services firm with milestone acceptance. A logistics provider with proof-of-delivery requirements faces different dispute drivers than a company whose invoices are purely time-and-materials. Therefore, the right receivables program is not copied blindly; it is designed around the operational realities that create disputes and delay payments.
Improvements usually come from clarity and process speed: accurate invoices, proactive reminders, easy payment options, transparent dispute resolution, and segment-based outreach. DSO reductions are top achieved by reducing avoidable friction rather than pressuring customers improperly.
Customer relationships suffer when collections looks like punishment rather than problem-solving. Best practices often include: early notification of missing information, a clear “how to pay” guide, responsive dispute handling, and professional escalation. In mature programs, customers perceive the company as organized and predictable, not as aggressive. That perception can actually improve payment timing because customers trust the process.
In the spirit of Receivables Investopedia-type education, it’s easy to stop at definitions. But the real value comes when those concepts translate into operations: credit terms that match risk, invoicing controls that minimize disputes, and a collections workflow that turns aging into cash. By adopting a structured, requirements-driven approach and monitoring aging trends, organizations strengthen liquidity, improve reporting credibility, and reduce the costly drag of unpaid invoices.
If you want, tell me your industry (e.g., manufacturing, SaaS, logistics) and typical invoice cycle time, and I can tailor a receivables playbook—credit policy outline, aging cadence, and dispute workflow—to your scenario.
To make that tailoring more useful, consider sharing a few additional details about your current process. For example: what percent of invoices are ever disputed, how quickly you resolve disputes, whether you experience unapplied cash, and whether your top customers pay on consistent schedules. With that information, it’s possible to pinpoint which levers will likely produce the fastest DSO improvement and which levers will reduce the risk of write-offs over the longer term.
Ultimately, receivables excellence is a system built on four principles: correctness (accurate billing and evidence), clarity (clear terms and payment instructions), responsiveness (fast dispute and collections workflow), and learning (continuous improvement using metrics). When those principles guide your process, accounts receivable stops being a periodic accounting burden and becomes a predictable component of cash conversion.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Digio Livelo Explained: Rewards Integration and Use
This guide explains how Digio Livelo works for earning and using rewards, what to verify before you start, and how to choose sensible redemption options. “Digio Livelo” refers to a rewards relationship between Digio’s digital banking/payment experience and Livelo’s loyalty ecosystem. Practically, it’s about matching your spending or engagement to reward accrual, then selecting redemptions that fit your goals.
Receivables Explained with Investopedia Insights and Risk Controls
This guide explains receivables fundamentals and how to manage them with evidence-based controls aligned with Investopedia-style definitions. It provides objective background on what “receivables” means in accounting, why aging matters, and how businesses assess credit exposure, collect payments, and protect cash flow without assumptions.
Accounts Receivable Guide: Investopedia Insights for Clarity
This guide explains how accounts receivable work, how they’re valued and managed, and how firms interpret them in decision-making. Background context covers the Receivables concept referenced by Investopedia, common risks like credit exposure and timing gaps, and the role of policies, documentation, and estimates such as allowances. The focus is practical and objective for analysts and operations leaders.
Receivables: How to Interpret and Manage Credit Risk
Receivables are the lifeblood of many businesses because they represent money owed by customers. This guide explains how receivables are analyzed, why payment terms matter, and how “Receivables Investopedia” concepts help standardize thinking about liquidity and credit risk. Objective background follows, centered on accounting definitions, risk signals, and common management practices.
Bambora Payfac: A Practical Guide for Merchants
Bambora Payfac helps merchants structure card and digital payments through a streamlined payment facilitation model. This objective guide explains what payment facilitation is, how onboarding and compliance typically work, and what merchants should evaluate—pricing transparency, risk controls, settlement timing, and operational responsibilities—so you can choose an approach that fits your business needs.
Understanding Accounts Receivable and Investopedia Insights
This guide explains how accounts receivable work, how to interpret “Receivables” definitions (including perspectives aligned with Investopedia), and how to manage invoice collections with disciplined policies. Accounts receivable refers to money customers owe from credit sales. It sits on the balance sheet as a current asset, and its quality affects cash flow, risk, and working-capital decisions.